

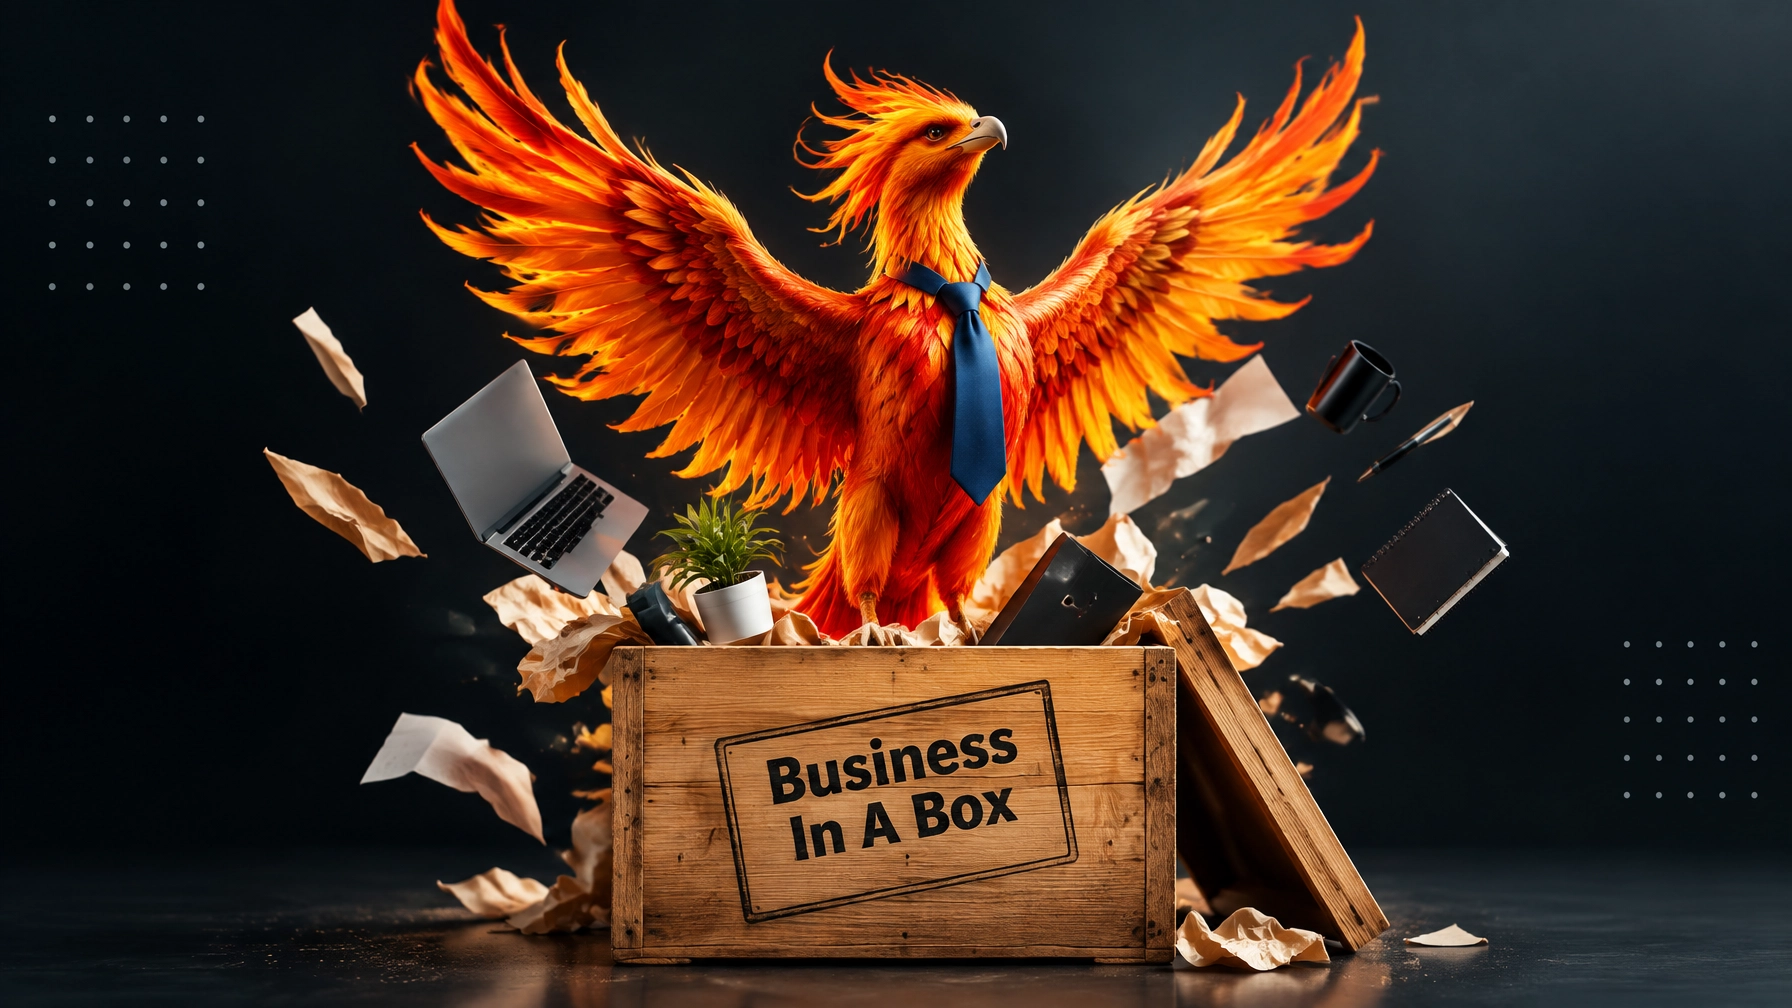
Launch beyond boundaries with a proven system, a clear plan, and a future that belongs to you.
A major life transition can make the future feel unrecognizable.
Divorce can change your household, finances, and identity at the same time. Bereavement can leave your calendar: and your home: strangely quiet. A layoff can remove the structure you relied on. Retirement can bring freedom but also an uncomfortable lack of purpose. Career burnout can make the work you once wanted feel impossible to return to.
You may want a fresh start. You may also be too exhausted to build an untested business from a blank page.
That is where franchising can become useful. A franchise is not a guarantee of success, and it is not a shortcut around hard work. But it can function like a business in a box: an established brand, operating procedures, training, marketing guidance, and a support network packaged into a defined business model.
For people navigating divorce, bereavement, job loss, empty nesting, retirement boredom, or burnout, that structure matters. Instead of inventing every process alone, you evaluate a system that already has operating procedures, vendor relationships, training, and a clearer path from opening day to daily execution.
The goal is not to escape your transition by making a rushed investment. The goal is to use this moment to build carefully, on terms that fit your finances, responsibilities, and desired lifestyle.
Buying a Franchise in the United States After Divorce
Divorce can create a powerful need for financial independence. You may suddenly be managing income, household expenses, insurance, debt, and long-term planning on your own. The desire to control your next chapter is understandable.
But ownership should begin with clarity, not urgency.
Before reviewing franchise brands, determine what your new financial reality actually looks like. Account for support obligations, housing costs, shared assets, legal expenses, and changes in household income. If you are using marital assets, settlement proceeds, or borrowed money, speak with the appropriate legal and financial professionals before committing.
A franchise may provide structure, but it still requires capital, time, and personal responsibility. The right opportunity should support your new life: not place additional pressure on it.
Begin with a business model that matches your available energy and preferred role. Some franchises require hands-on daily operations. Others are designed for owners who lead a manager and focus on growth. Neither approach is automatically better. The right choice depends on your financial runway, management experience, and family obligations.
Finding a Franchise After Job Loss or Career Burnout
A layoff can affect more than your paycheck. It can challenge your confidence and disrupt the routine that gave your days direction. Burnout creates a different problem: you may still have valuable experience, but you no longer want to repeat the conditions that drained you.
Franchising can offer a middle path between returning to corporate employment and inventing a company from scratch. You can own the business while using an existing playbook. Your experience in sales, operations, leadership, finance, customer service, or project management may transfer well: even if you have never worked in the franchise industry.
Keep an open mind about industries. Many franchise owners enter sectors where they have no prior technical experience because the franchisor provides training and operating guidance. The more important questions are:
- Do you want to manage people, serve customers, sell, operate, or build relationships?
- How many hours can you realistically work?
- Do you want a local storefront, a mobile service business, or a home-based model?
- What responsibilities do you never want to repeat?
A franchise can give you a framework. It cannot decide whether the framework fits your life. That decision requires honest self-assessment.
Starting a Franchise After Bereavement
After losing a spouse or another close family member, work can provide routine when everything else feels unsettled. A new business can also create a sense of purpose and community.
However, grief does not follow a business timeline. If the loss is recent, do not assume that a major investment will solve the emotional pain. It may be wise to wait until you can evaluate opportunities without feeling pressured to fill an empty space immediately.
When you are ready, look closely at the support built into the franchise model. Review the training schedule, field support, technology, staffing expectations, and owner workload. A system that depends entirely on you being available every day may not fit your current capacity.
A business can become part of a new routine, but it should not become your only source of identity or support. Build a team around yourself, including a franchise attorney, CPA, lender, trusted family members, and people who understand what you are navigating.
Rebuilding After Retirement or an Empty Nest
Retirement and empty nesting can create a different kind of transition. You may have more time and experience than ever, yet fewer built-in reasons to use them.
A franchise can provide structure, social connection, and a productive challenge. It can also become a business asset that you may eventually sell or transfer. But retirement capital requires particular care. Money invested in a franchise may no longer be available for healthcare, living expenses, travel, or unexpected needs.
Use a separate business budget and household budget from the beginning.
Your business budget should account for the full franchise investment, including the franchise fee, equipment, build-out, technology, insurance, licenses, inventory, marketing, payroll, rent, professional services, and working capital.
Your household budget should remain separate. Include mortgage or rent, food, healthcare, taxes, debt payments, transportation, family support, and personal reserves. Do not assume the business will immediately pay you a salary.
The FTC advises prospective franchise owners to estimate both operating expenses and personal living expenses, potentially for up to two years, because some businesses take more than a year to reach break-even. Read the FTC’s Consumer’s Guide to Buying a Franchise before making a decision.
Read the Franchise Disclosure Document Before You Commit
Every serious franchise evaluation should include a complete review of the franchisor’s Franchise Disclosure Document, or FDD. The FDD contains 23 disclosure items designed to help you investigate the opportunity.
Do not rely on a presentation, sales call, earnings conversation, or promotional event in place of the FDD. Pay particular attention to these sections:
Item 7 : Estimated Initial Investment: Review the full range of costs, not only the franchise fee. Test the high end of the estimate and add a cushion for delays, cost overruns, and a slower launch.
Item 11 : Franchisor’s Assistance, Advertising, Computer Systems, and Training: Understand what training is included, how long it lasts, who pays for travel, what ongoing support looks like, and how advertising contributions are used.
Item 17 : Renewal, Termination, Transfer, and Dispute Resolution: This section explains how you can renew, sell, transfer, or exit the business. Pay attention to personal guarantees, noncompete provisions, termination rights, and arbitration requirements.
Item 19 : Financial Performance Representations: Any franchisor earnings claims generally must appear here. Review the source, assumptions, time period, number of units represented, and whether the figures show gross sales or actual profitability. Gross revenue is not take-home income.
Item 20 : Outlets and Franchisee Information: Study openings, closures, transfers, and ownership changes. Use the current and former franchisee contact information to conduct your own validation.
Under the FTC Franchise Rule, you must receive the FDD at least 14 days before you are asked to sign a contract or pay money to the franchisor or its affiliate. That 14-day period is a minimum review window, not a countdown to pressure you into a decision. Ask for an updated FDD before signing if the document has changed.
Have a franchise-experienced attorney review the FDD and franchise agreement. Ask a CPA or qualified financial professional to examine the assumptions and build a conservative financial model.
Call Franchise Owners and Build a Conservative Model
Franchise sales materials show the opportunity. Franchisees show the operating reality.
Call owners listed in Item 20, including both newer and more established operators. Speak with owners in markets similar to yours and ask:
- How much did the business actually cost to open?
- How long did it take to reach break-even?
- What costs were higher than expected?
- How useful was the training?
- How responsive is the franchisor today?
- What would they do differently?
- Knowing what they know now, would they invest again?
Do not only call the franchisees a sales representative recommends. Contact several people from the FDD list, including former franchisees when possible.
Then build your own conservative model. Use the higher end of startup costs, slower customer growth, realistic payroll, full royalty and advertising obligations, and no owner income during the early period unless the evidence supports it. Run a downside scenario. If the business only works under perfect conditions, it does not work yet.
Find the Right Franchise for Your Next Chapter
You do not need to choose from thousands of opportunities alone. FranLift provides free franchise matching and consultation to help identify brands that align with your goals, budget, experience, and desired lifestyle. The franchise companies pay FranLift as part of their marketing budgets, so there is no consulting fee to you.
FranLift can help you compare industries, understand the ownership model, connect with franchise attorneys and funding partners, and narrow the field to opportunities worth investigating. Learn more about how FranLift helps prospective owners find the right fit or contact FranLift to begin a confidential conversation.
A transition does not have to define the rest of your life. It can become the point where you stop rebuilding someone else’s plan and start designing your own.
Start carefully. Read everything. Protect your household. Then choose the business that gives you structure without taking away the life you are trying to build.
FranLift : Launch Beyond Boundaries.
This article is for general educational purposes and is not legal, tax, investment, or financial advice. Consult qualified professionals before purchasing a franchise.
