

A phoenix in a ghost costume makes a memorable case for considering what comes after Halloween.
The One Night A Year When Everyone Gets To Be Someone New
Halloween gives everyone permission to try on another identity. For a few hours, the neighbor who waves from the driveway becomes a vampire; a colleague turns up as a superhero; a bedsheet and a pair of eyeholes can make anyone a ghost. There’s candy in the bowl, costumes on the porch, and a little room to imagine a different version of yourself.
Then November 1 arrives. The costume comes off. The decorations go into a box. The alarm rings, the inbox fills up, and the old routine is waiting where you left it.
If you spent another October daydreaming at your desk about a different way to work or live, that feeling deserves your attention. Not because Halloween is a deadline to make a dramatic move, but because a recurring thought can be useful information. Maybe you want more independence, more ownership of your work, or a path that feels like it belongs to you.
Separate that feeling from the decision. A holiday can prompt an honest question; it cannot tell you whether a particular business is right for you. You don’t have to buy anything this week. You can start by examining what a fresh start would actually ask of you, and what you want it to make possible.
An Honest Look At Whether A Fresh Start Fits Your Real Life
Start with your finances, not the most inspiring franchise brochure. Estimate how much capital you could responsibly commit without putting essential savings or obligations at risk. Include the full cost of getting open and operating: the franchise fee, equipment, build-out or lease costs, insurance, professional fees, payroll, required supplies, and working capital. Ask what expenses may arrive before the business has steady revenue.
Then look at debt honestly. What monthly payment could you manage if sales grow slowly? How would repayment affect your household budget? A plan that only works when every early estimate comes true is not a conservative plan.
Your time and energy matter just as much as your capital. Consider health needs, caregiving, family commitments, and the hours you can realistically spend building a business. Be specific about the work you want to do. Do you enjoy customer interaction and day-to-day operations? Would you rather lead employees and focus on hiring, sales, and performance? A manager-run business is not passive ownership: you still need to oversee people, cash flow, standards, and problems.
Write down your non-negotiables before talking to brands or advisors. These might include maximum investment, location, time away from home, preferred work style, or the amount of debt you are willing to take on. Add a few deal-breakers. Your list gives you a practical filter when excitement, or pressure, starts to crowd out the facts.
The costume can come off; the questions about your next chapter can stay on the notepad.
Treat The FDD Like A Map, Not A Promise
The Franchise Disclosure Document (FDD) is a key tool for understanding a franchise opportunity. The FTC Franchise Rule generally requires a franchisor to provide the FDD at least 14 calendar days before you sign a binding agreement or pay the franchisor or an affiliate. Treat that as a minimum review window, not a recommendation to finish your diligence in two weeks. Ask for the complete, current document and record when you receive it.
Read Item 19 with care. It may contain financial-performance information, such as sales or other results, but the franchisor is not required to provide an Item 19 representation. If it does, ask for the written substantiation behind it and understand exactly what the figures include, and leave out. An example is not a promise of what your location will earn. Be cautious about earnings claims made in a call or presentation that do not appear in the FDD.
Item 20 helps you examine the franchise system’s movement over time, including openings, closures, and transfers. It also provides contact information for current franchisees and certain former franchisees. Speak with both groups; don’t rely only on references suggested by the franchisor. Ask current owners what the opening process, training, support, staffing, and actual costs were like. Ask former franchisees why they left, what they wish they had known, and whether their experience matched their expectations. Compare what you hear with the FDD.
Have an independent franchise attorney review the FDD and agreement. Ask a CPA to examine the financial assumptions and help you test whether the numbers make sense for your situation. They work for you, not the franchisor, and can help surface questions you might otherwise miss.
Due diligence can be serious work, even when the ghost costume and candy bowl are still around.
Match The Money To A Conservative Plan
Financing can be part of a sound plan, but don’t build your decision around money you have not secured. The SBA Franchise Directory can help you check whether a franchise brand is eligible for SBA financial assistance. Being listed is not an endorsement or approval of the brand, and it does not ensure the business will succeed.
An SBA 7(a) loan may be used for eligible business purposes, including changes of ownership and working capital. The SBA 7(a) loan program has eligibility requirements, and you apply through a lender. Financing is not guaranteed; lender underwriting and your ability to repay matter. Discuss the terms, fees, collateral, guarantees, and repayment schedule with lenders before relying on a loan in your plan.
Build a conservative model with monthly estimates, not just a best-case annual total. Include personal living expenses alongside business costs, and assume first-year revenue may take time to build. Model a slower opening or lower sales than you hope for. Keep a cash reserve for unexpected costs and for the gap between opening and reliable cash flow. If your downside case puts your household or business at unacceptable risk, pause and revise the plan.
Explore Franchise Opportunities With FranLift
A franchise can be a “business in a box”: training, operating manuals, established procedures, brand standards, ongoing support, and a peer network of owners. These resources can reduce uncertainty compared with figuring out every system alone. They do not remove the demands of ownership or guarantee success. The right fit still depends on your finances, goals, working style, market, and the specific franchise you investigate.
FranLift helps prospective owners explore opportunities that may align with their goals, lifestyle, and budget. Learn how FranLift works or start a conversation. A first conversation is a way to clarify what you’re looking for, not a commitment to buy. FranLift’s service is free to buyers because franchisors cover the cost as part of their marketing budget.
A consultant can help you explore and compare options, but is a guide, not a substitute for independent legal, accounting, tax, or financing advice. Take the time you need to ask questions, check the details, and decide whether an opportunity fits the life you actually have.
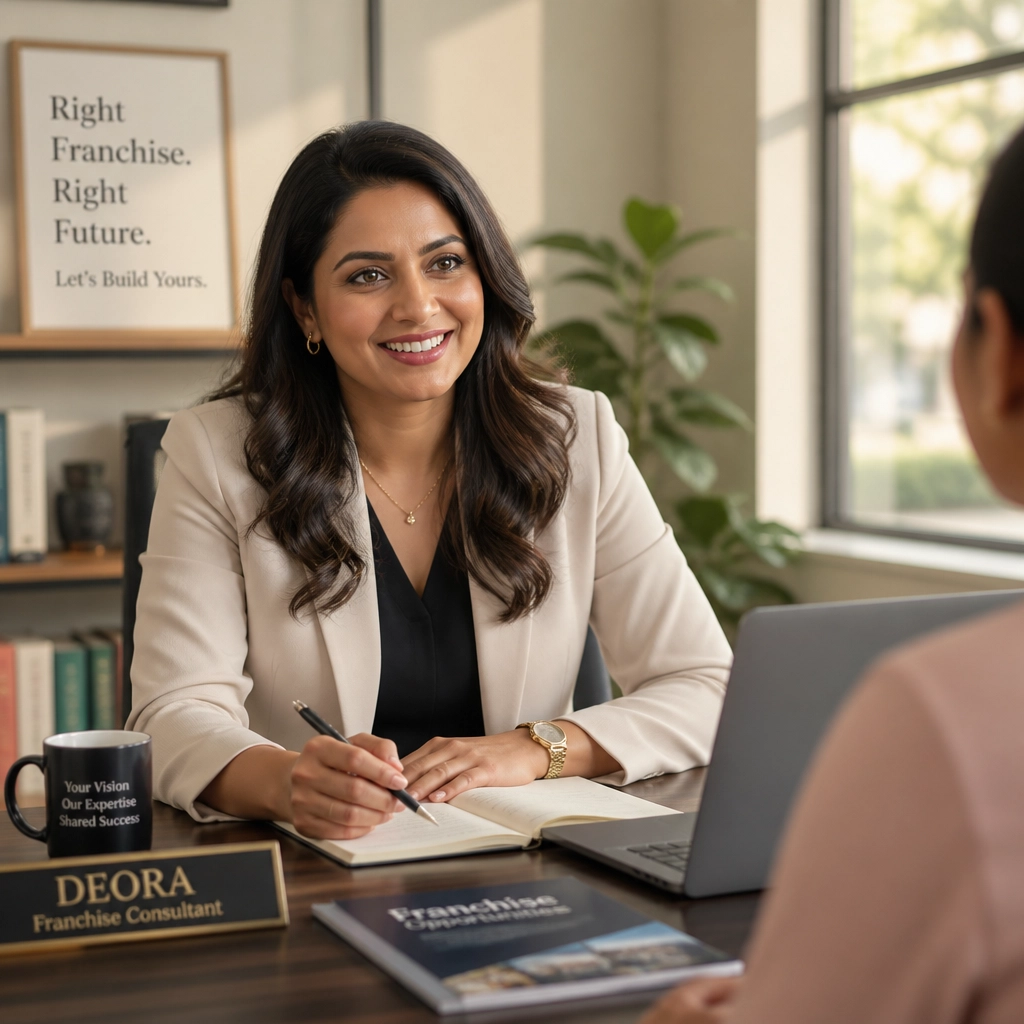
Deora Pollock, FranLift franchise consultant, in a professional consultation setting.
Make the next step an informed one.
Launch Beyond Boundaries.
This article is for informational purposes only and is not legal, accounting, tax, investment, or financing advice. Franchise terms, costs, eligibility, and financing availability vary. Review the current Franchise Disclosure Document and all agreements with an independent franchise attorney, consult a qualified CPA and tax professional, and confirm financing terms directly with lenders before making a decision. No franchise opportunity or financing is guaranteed to produce a particular result.
© 2026 FranLift
