

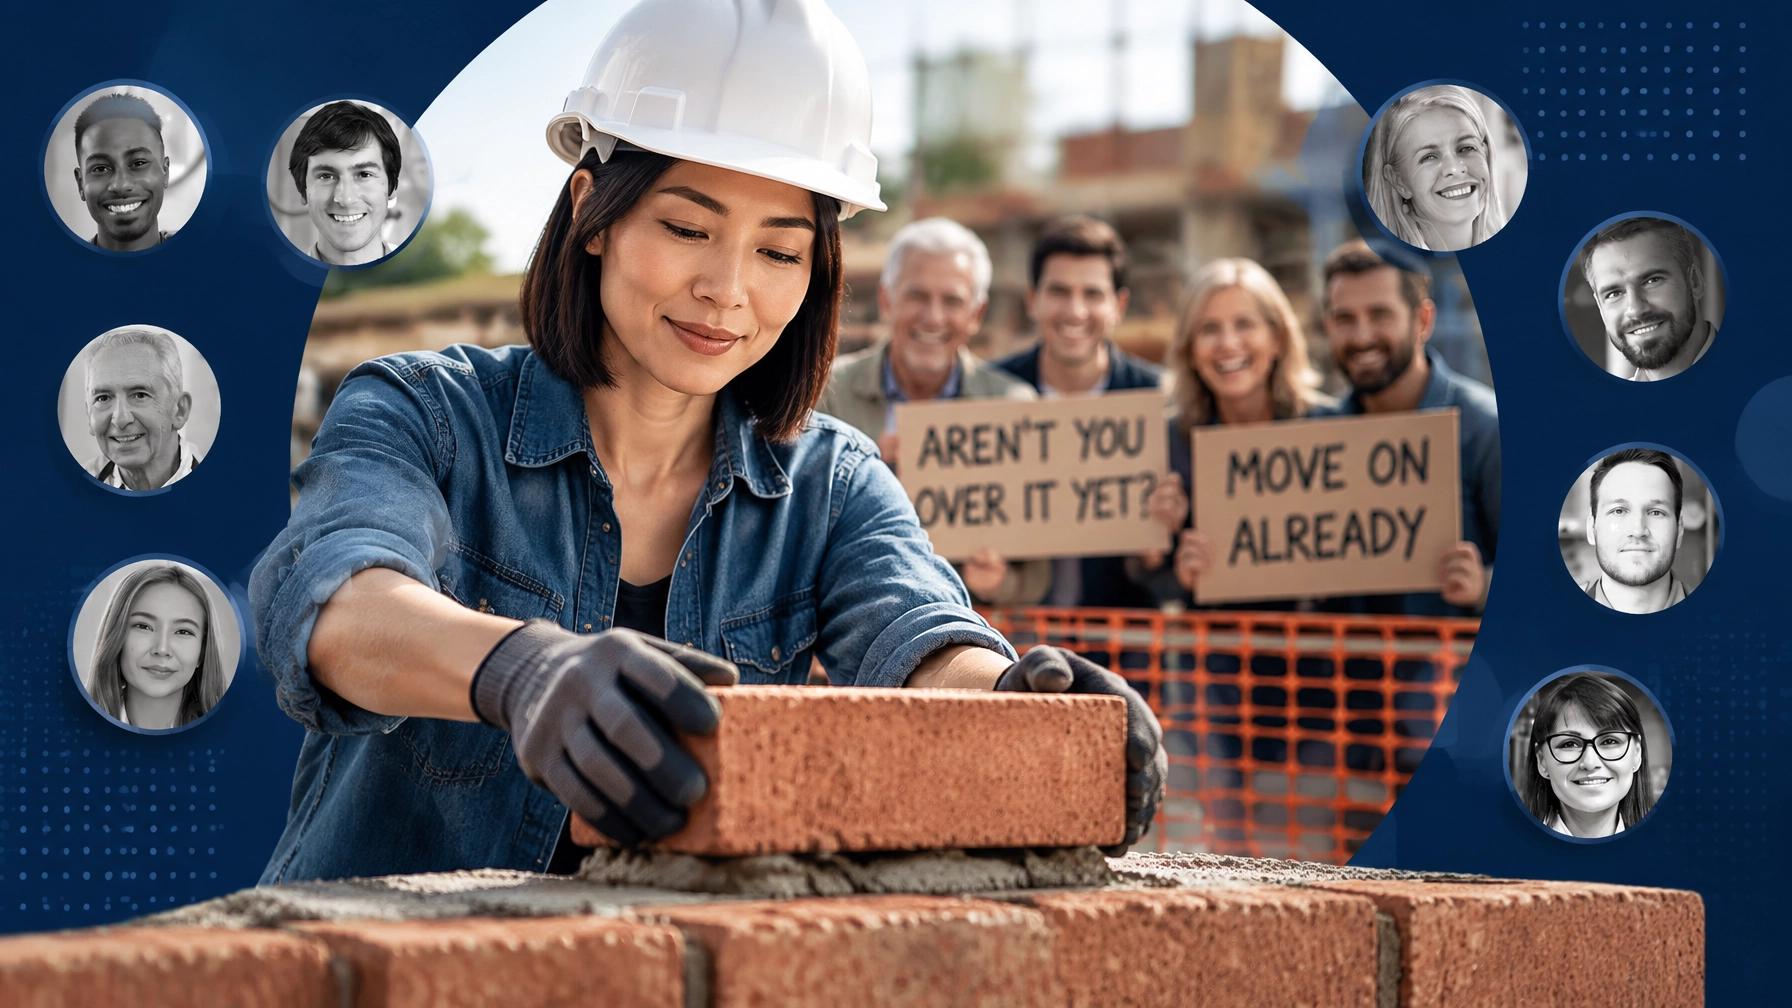
There is often a second wave after a major life change. At first, people check in. They bring food, offer help, and make space for what happened. Then the messages slow down. Months pass, and someone asks, “Aren’t you over it yet?” or “Shouldn’t you be ready to move on?”
Those questions can make a difficult transition feel even more isolating. But recovery and rebuilding don’t follow someone else’s calendar. Whether you’re considering a career change, navigating a loss, or adjusting to a new household, you can take time to decide what comes next.
For some people, franchise ownership may be one way to explore a new direction. A franchise can offer a defined operating system, a kind of “business in a box”, when life feels uncertain. It is still a real business, with real costs and risks. The aim is not to rush into a fresh start, but to find out whether ownership fits your goals, finances, and timeline.
Divorce: Don’t Invest To Prove You’re Fine
Relatives may encourage you to get back out there, make a big move, or show everyone you’re doing well. But a major business investment shouldn’t be a performance for other people.
Divorce can reshape your household finances, housing, debt, and responsibilities. Before considering a franchise, understand how a potential investment could interact with shared or separate assets, settlement terms, taxes, and guarantees. Set aside money for living expenses, legal costs, insurance, and emergencies before deciding what you can risk.
Exploring opportunities can be a useful first step. Signing just to reassure other people, or yourself, that you’re fine is not a sound investment strategy.
Grief And Bereavement: There Is No Deadline
Grief doesn’t end because a certain number of months have passed. If other people seem ready for you to move on, that doesn’t mean you have to be.
A business may eventually give you a new routine or goal, but it cannot replace the person you lost or resolve grief. Avoid making a major investment just to fill an absence. You can research franchise models, ask questions, and revisit the idea later. Exploration doesn’t require commitment.
If you’re considering using inherited or survivor assets, get independent financial advice before deciding what portion, if any, is appropriate to invest.
Job Loss: Plan For The Income Gap
At gatherings, “Still looking?” can land like a verdict. A layoff can be painful and disruptive; it can also prompt a person to consider a different route to work. But a franchise rarely provides immediate income on demand.
Before you invest, estimate the time and money needed to open, attract customers, and operate the business. Build a month-by-month budget that includes both business costs and your household’s income gap. Ask what happens if opening takes longer than expected or sales ramp up more slowly. Consider whether keeping other income options open makes sense while you research.
A franchise system may provide training and an operating process. It cannot guarantee when you’ll earn income or how much.
Empty Nest: Choose The Working Week You Want
People may assume that once children leave home, you’ll immediately downsize, travel, or reinvent yourself. You don’t have to choose a new identity, or a new business, on anyone else’s schedule.
Start with the week you want to live. Do you want regular customer contact, a team to manage, flexible hours, or work that is mostly behind the scenes? Franchise ownership can be hands-on, and the day-to-day reality may not match the appealing idea of “being your own boss.” Talk with franchisees about their actual responsibilities and hours, then consider whether that working week fits your priorities.
Retirement Boredom: Add Purpose Without Betting Your Security
A casual “What do you do all day?” can make a change in routine feel like a problem to solve. If you want a project, community, or more structure, business ownership may be worth exploring. It may also require more time, energy, and capital than you expect.
Set firm boundaries around your retirement savings, essential living costs, and emergency reserves. Ask about staffing, owner involvement, and the time it may take for the business to reach break-even. Do not risk money you need for your financial security just to silence someone else’s comment.
Career Burnout: Don’t Buy A New Version Of The Same Problem
Colleagues may expect you to bounce back quickly, as though a new role, or a new business, will automatically make things better. But ownership can bring long hours, customer demands, staffing challenges, and contractual rules.
Before pursuing a franchise, pinpoint what you need to change. Is it the work itself, your schedule, your manager, or the level of control you have? Then compare those needs with the actual work of a franchise owner. Ask current franchisees what takes most of their time, what surprised them, and what they find difficult. Don’t buy a business just because it looks like an exit from burnout.
Structure Can Help, But It Does Not Remove The Work
Starting independently means creating your own brand, processes, training, and marketing. A franchise may provide some of that structure: a system to learn, initial training, and ongoing support described in the franchise documents. That framework may be useful when other parts of life feel unsettled.
“Business in a box” does not mean risk-free, turnkey, or guaranteed. You still need to operate the business, serve customers, manage costs, and follow the franchise agreement. Startup expenses can extend beyond the initial franchise fee, and ongoing fees may be due even when the business is not profitable. A franchise may offer a clearer starting point than building everything from scratch, but it does not remove the decisions or uncertainty.
How To Buy A Franchise On Your Own Timeline
You don’t need to make a decision immediately. Begin with a written self-assessment: the work you want to do, the hours you can sustain, your income needs, your maximum investment, and the risks you cannot accept. Include personal considerations such as caregiving, health coverage, debt, or a period without household income.
Next, build a full budget. Include franchise fees, equipment, rent or workspace, insurance, professional services, marketing, payroll, and working capital, as applicable. Add your household expenses during the opening period and a reserve for delays or lower-than-expected sales. Test conservative assumptions as well as more optimistic ones. If the plan only works under ideal conditions, pause.
A franchise consultant can help narrow a large field of brands and coordinate introductions. FranLift offers free matchmaking to buyers; franchise companies cover the cost as part of their marketing budgets. Ask how a consultant’s process works and which brands they represent. A consultant can help you explore options, but does not replace independent legal, tax, or financial advice.
Read The FDD And Check The Details
Before you invest, read the franchisor’s Franchise Disclosure Document (FDD). The FTC’s guide to buying a franchise explains how to use it. The FDD contains 23 disclosure items, and the FTC Franchise Rule generally requires you to receive it at least 14 calendar days before signing a binding agreement or paying the franchisor or its affiliate.
Pay particular attention to Item 19, which may contain financial performance representations if the franchisor chooses to provide them. The Rule does not require a franchisor to make these representations. Review the assumptions and what the figures include or exclude; sales are not the same as profit. Treat earnings claims made outside the FDD as a reason to ask careful questions.
Item 20 provides information about franchise outlets and franchisee contacts. Review the system’s openings, closures, and transfers, then speak with current and former franchisees. Ask about actual costs, training, support, workload, and what they would want a prospective owner to know.
Before signing, have an independent franchise attorney review the FDD and agreement. An independent CPA can help assess the business’s costs and the assumptions in your budget. If you’re considering financing, review the SBA’s guidance on buying a business or franchise and discuss your situation with a lender. Financing eligibility does not guarantee business success.
Take The Next Step When It Fits
Your next chapter doesn’t have to begin on the day other people think it should. You can ask questions, compare options, and decide that the right next step is to wait. If franchise ownership remains worth exploring, learn how FranLift helps buyers or contact the team to start a conversation.
Move at a pace that leaves room for both ambition and careful due diligence. The decision should fit the life you are building, not the timeline someone else has set for you.
FranLift is not a legal, tax, or financial advisor. Consult qualified independent professionals before making investment decisions. Franchise ownership involves risk, and no income or business outcome is guaranteed.
Launch Beyond Boundaries.
© 2026 FranLift. All rights reserved.
