

An extra hour on the clock can make room for a useful question: Is your working life still the one you want?
The Night The Clocks Fall Back
Overnight, in most places that observe daylight saving time, the clock gave you an hour back. It’s a peculiar little gift: one more hour to sleep, read, scroll, or wonder why there are already holiday decorations in stores.
Then the evenings keep getting darker earlier. In many parts of the country, it can feel as though the day is winding down before dinner. That shift may make the routines of work and home more visible: the commute, the late meeting, the Sunday-night inbox, the job you keep imagining doing differently.
If that daydream keeps coming back, it’s useful information. It isn’t proof that you should quit, buy a business, or make a dramatic change by Monday. A clock reset is a prompt to reflect, not a deadline to sign anything.
Time is the one thing you can’t earn back. So consider what this extra hour shows you about how you spend yours, and whether your current chapter of work fits the life you want. The answer might be “yes, with a few adjustments.” It might be “I want to explore something new.” Either way, separate the feeling from the decision. Let the feeling start a thoughtful inquiry; let evidence guide what happens next.
An early-dark evening can be a good time to pause and take stock.
An Honest Look At Whether A Fresh Start Fits Your Real Life
Before exploring a franchise, get specific about the life you want it to support. Start with your money. Decide how much capital you could responsibly commit without putting essential needs or your financial stability at risk. Then look beyond the franchise fee. The full cost may include equipment, build-out, lease expenses, insurance, professional fees, payroll, inventory, and working capital. The details vary by brand and business model, so get the actual figures for each opportunity you consider.
Next, ask what debt you can tolerate and what obligations you already have. A business plan should account for more than the business. Include personal living expenses and the possibility that revenue builds slowly.
Your time, energy, health, and family responsibilities matter just as much. Some franchises require an owner to be hands-on day to day. Others may allow an owner to lead through a manager, but manager-run ownership is not passive. Hiring, supervision, financial oversight, and accountability still take work. Ask what the role actually looks like in practice, including during the opening period.
Write down your non-negotiables and deal-breakers. Maybe you want predictable hours, a specific investment range, or a business that doesn’t depend on a retail location. Maybe you don’t want to manage a large staff. The point is not to find a perfect opportunity; it’s to make your criteria clear enough to assess fit.
A franchise can offer a “business in a box”: training, operating manuals, established procedures, brand standards, ongoing support, and a peer network of owners. Those systems may reduce some uncertainty compared with building everything from scratch. They do not remove the work, eliminate risk, or guarantee results. The quality and scope of support differ by franchisor, so verify what’s provided and what owners say they receive.
Treat The FDD Like A Map, Not A Promise
The Franchise Disclosure Document (FDD) is a central source of information about a franchise. Under the FTC Franchise Rule, a franchisor generally must provide the FDD at least 14 calendar days before you sign a binding agreement or pay the franchisor or an affiliate. Use that review period. Don’t let a seasonal mood, sales conversation, or imagined deadline rush you through it.
Read Item 19 carefully. It may include financial performance representations, but it is information to evaluate, not a promise about what you will earn. If a financial claim matters to your decision, ask for the written substantiation and make sure you understand how the figures were calculated, which locations they cover, and whether they apply to your market and circumstances.
Item 20 can help you understand the franchise system’s outlet activity, including openings, closures, transfers, and franchisee contacts. Look at the pattern, not just one figure. Call current franchisees to ask about training, support, staffing, costs, and the realities of daily operations. Call former franchisees too, and ask why they left. Their experiences can add context that the paperwork alone cannot provide.
Have an independent franchise attorney review the FDD and agreement, and ask a CPA to evaluate the financial information. A franchisor’s materials, and anyone helping you explore the opportunity, are not substitutes for your own professional advice.
Match The Money To A Conservative Plan
Build a monthly plan that tests what happens if the first year is slower than you hope. Include business costs such as rent, payroll, insurance, royalties, marketing fees, debt payments, and ongoing supplies. Include your personal living expenses, too. Then estimate how much cash you would need to cover the gap while revenue develops, and decide what reserve you would want to keep available.
Use cautious assumptions rather than best-case projections. Ask which costs are fixed, which change with sales, and what happens if opening takes longer or expenses run higher than expected. A financial plan is not a prediction; it’s a way to see what the opportunity would require from you, and whether the downside is manageable.
The SBA Franchise Directory can help lenders assess whether a franchise is eligible for SBA financial assistance. Being listed is not an SBA endorsement or approval of the brand, and it does not ensure the business will succeed. Similarly, the SBA 7(a) loan program may support certain business financing needs, but financing is not guaranteed. Eligibility, approval, terms, and repayment capacity depend on your situation and the lender’s review.
The piggy bank looks optimistic; your cash-flow plan should be realistic.
Explore Franchise Opportunities With FranLift
If you’re ready to explore, not commit, FranLift can help you narrow the field. We start with a conversation about your goals, budget, preferences, and constraints, then research and curate potential franchise matches. We can also help facilitate introductions and connect you with franchise attorneys and funding partners.
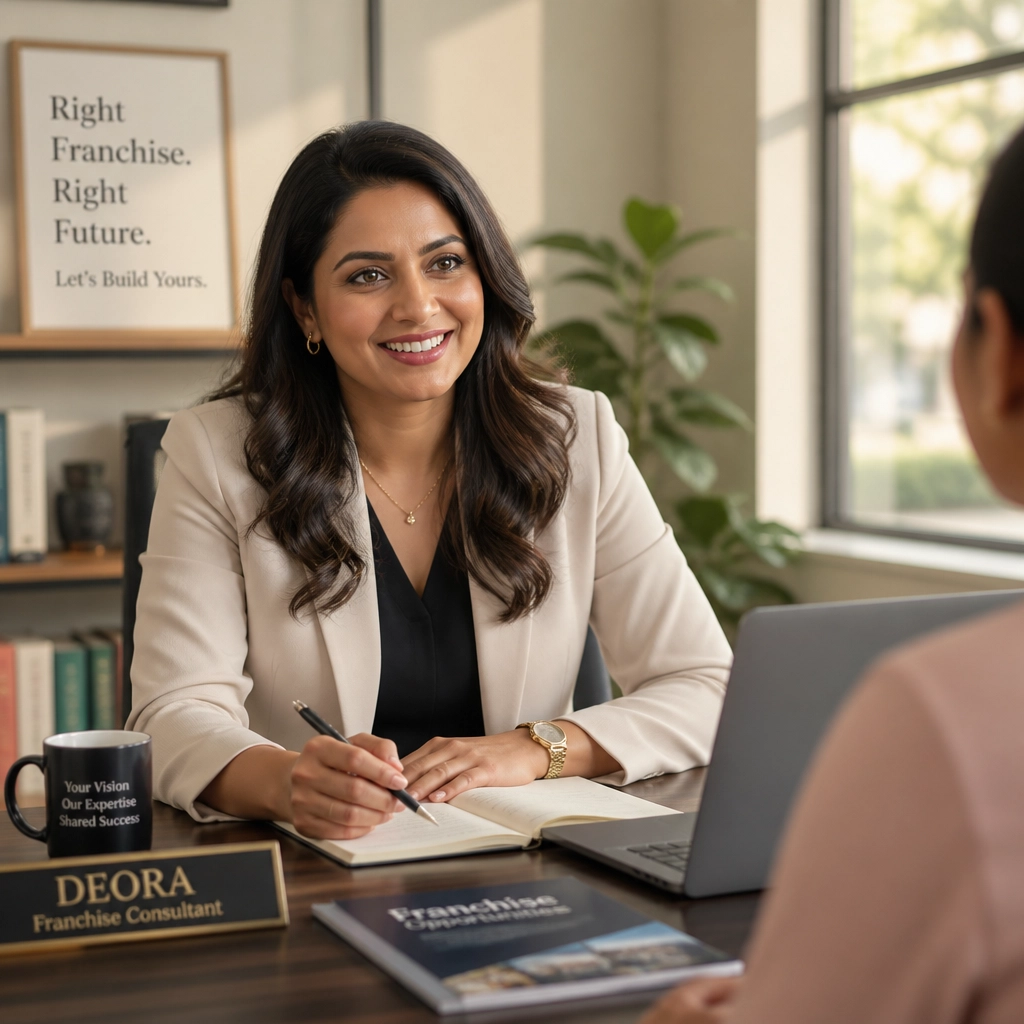
Deora Pollock, FranLift franchise consultant, in a professional consultation setting.
The service is free to buyers because franchisors cover the cost as part of their marketing budget. Learn more about how FranLift works or start a conversation. A first conversation is not a commitment to buy, or even a commitment to pursue franchising. It’s a chance to ask questions and see whether exploring further makes sense.
A consultant can help organize your search, but can’t replace independent legal, accounting, tax, or financing advice. Your decision should rest on your priorities, the documents, professional guidance, and a careful review of the actual opportunity.
Make the next step an informed one.
Launch Beyond Boundaries.
This article is for informational purposes only and is not legal, accounting, tax, investment, or financing advice. Review the FDD with an independent franchise attorney; consult a CPA and tax professional; and confirm financing directly with lenders. No business or financial outcome is guaranteed.
© 2026 FranLift
