

A layoff can turn a familiar calendar into a blank page. Divorce can reshape your finances and daily life at once. After bereavement, retirement, an empty nest, or career burnout, even deciding what comes next can feel like work.
It makes sense to want a plan, and a franchise can offer one: a recognized brand, operating systems, training, and support. Think of it as a business in a box, not a paycheck in a box. You still have to run the business, serve customers, manage people, and carry financial risk.
The title’s warning is about your financial runway, not a universal deadline on severance. Cash has a way of shrinking as monthly expenses continue, while decisions about benefits, taxes, family obligations, and business costs may need attention. The goal is to explore franchise opportunities while you still have time to think clearly, not to rush into a purchase.
Job Loss: Calculate Your Runway Before You Shop
Severance can feel like breathing room. But before treating it as startup capital, work out how long it can support you and your household if the business produces no income at first.
Start with a conservative monthly budget. Include housing, debt payments, healthcare, taxes, and other essential costs. If you’ve lost employer-sponsored health coverage, account for replacement coverage. Then set aside money needed for legal obligations, taxes, and emergencies. What remains is not automatically available to invest.
A franchise may require an initial fee plus equipment, inventory, insurance, lease costs, payroll, marketing, and working capital. Opening may take longer than expected, and early sales may not cover expenses, or pay you. Keep personal reserves separate from the business budget, and model a slower opening and lower sales than the optimistic case.
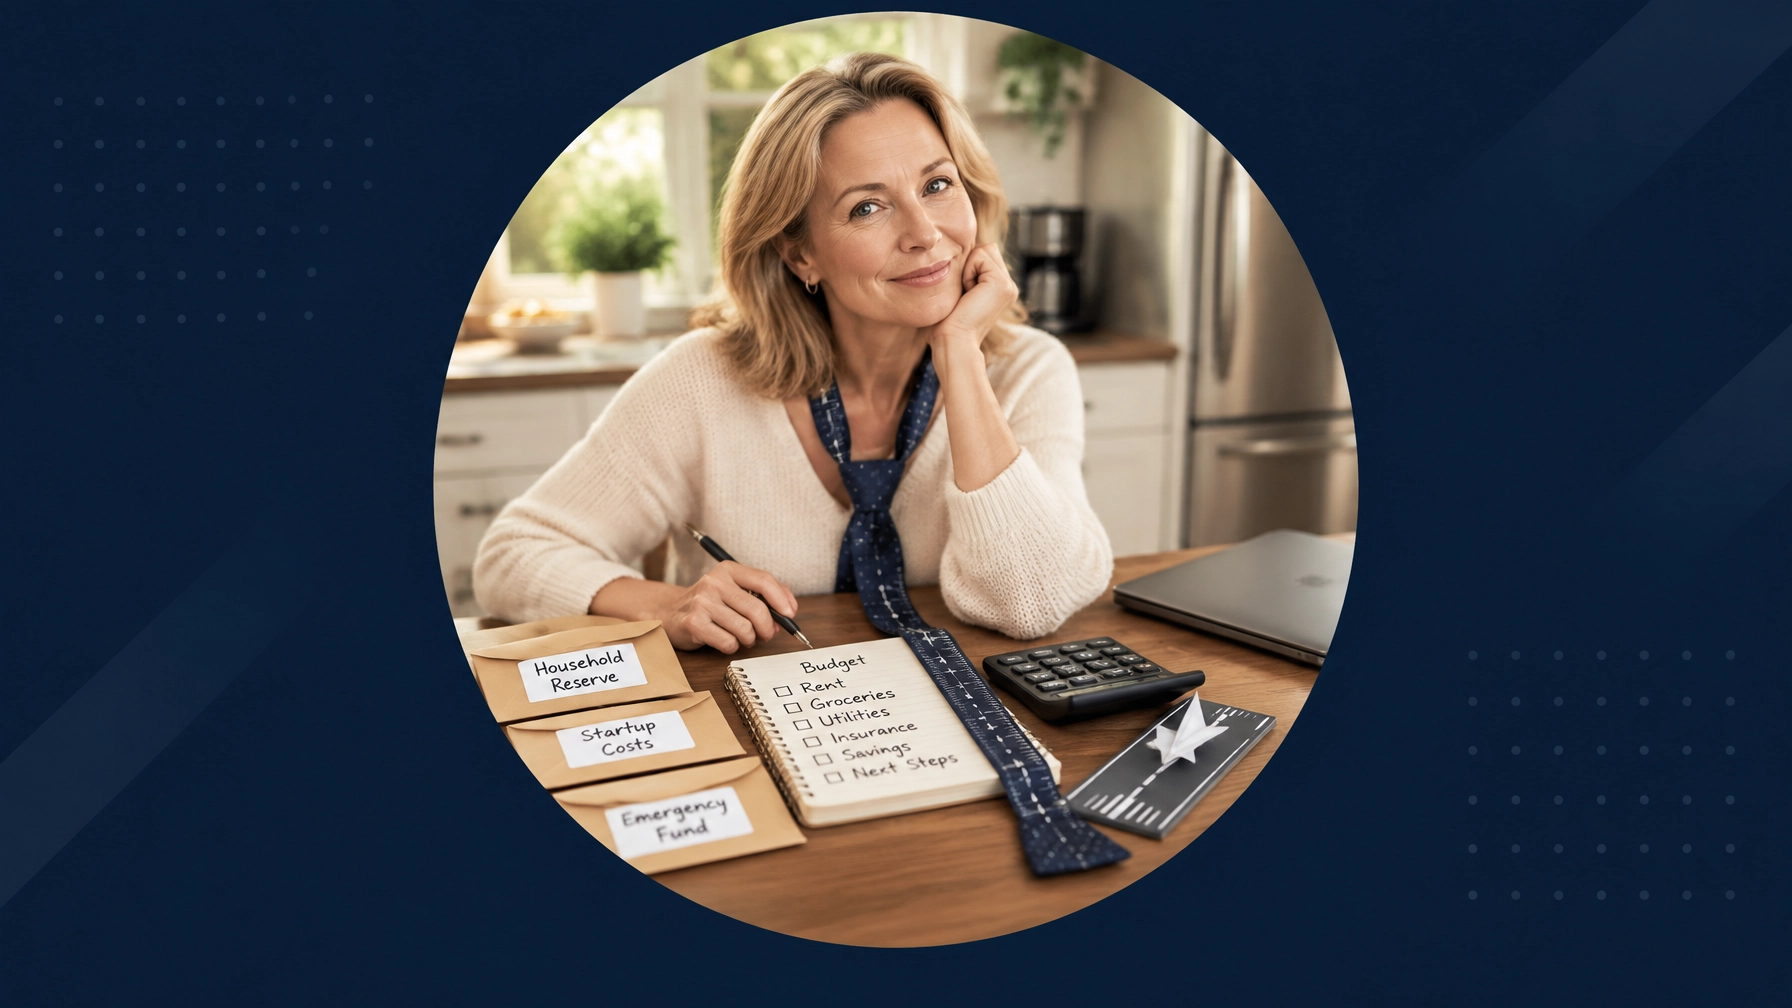
If the numbers only work when you take a salary right away or use money needed for basic security, pause. Continuing to work, consulting, or researching while you stabilize your finances may be a stronger next step than trying to force a purchase into a short runway.
Divorce: Protect Your Financial Reset
Divorce can change your income, housing, savings, and responsibilities at the same time. Wanting to take control of your future is understandable. But if assets are still being divided, don’t assume a balance is yours to invest, or that it should be.
Get a clear picture of your post-divorce budget, obligations, and available funds. Ask your family-law attorney and an independent financial professional what money is actually available and what risks a business investment could create. Keep funds for housing, support obligations, legal costs, and emergencies out of the franchise budget.
A fresh start should increase your options, not put your basic stability at risk.
Bereavement: Research Without Asking a Business to Fix Grief
After someone dies, a new routine or project may eventually feel welcome. You don’t have to decide immediately. You can learn how franchising works, talk with owners, and consider what kind of work might suit you without signing anything.
If an inheritance or estate funds could be involved, confirm what is available after obligations and expenses with qualified advisers. A franchise might provide structure when you’re ready. It cannot replace the person you lost, and it shouldn’t be expected to.
Empty Nest and Retirement: Choose the Work, Not Just the Idea
When the house gets quieter or retirement leaves more open time, business ownership can offer a new focus. Start by picturing an ordinary Tuesday. Do you want to lead employees, work directly with customers, travel locally, or keep evenings free?
A storefront, home-based service business, and mobile operation can come with very different costs, schedules, and staffing demands. None is automatically flexible or passive. Ask franchisees what the owner actually does each week, how much time the business requires at launch, and what “semi-absentee” means in practice.
If retirement savings or future income are involved, get independent advice before investing. Available time is not the same as available capital.
Career Burnout: Don’t Buy a New Version of the Same Job
If your career has left you depleted, being your own boss may sound like an escape. It is not an escape from responsibility. Depending on the franchise, your work could involve selling, hiring, scheduling, customer complaints, and weekend hours.
Write down what you need to leave behind: long hours, travel, lack of control, or the work itself. Then compare those needs with the franchise’s actual day-to-day demands. The best franchises to own are not simply the most familiar or popular; they’re the ones whose business model, costs, and responsibilities fit your goals and resources.
How to Buy a Franchise Without Rushing the Decision
Begin with your life, not a brand presentation. Set a maximum investment that protects personal essentials. Decide how much time you want to work, which responsibilities you’re willing to take on, and how long you can manage without income from the business. Compare those limits with the total startup investment, ongoing fees, training, territory, owner hours, and time to open.
Before signing or paying, review the franchisor’s Franchise Disclosure Document (FDD). The FTC’s guide to buying a franchise explains the information to investigate. In general, the FTC Franchise Rule requires you to receive the FDD at least 14 calendar days before signing a binding agreement or paying the franchisor or an affiliate. That’s a minimum disclosure period, not a deadline to finish due diligence.
Pay particular attention to the estimated investment and fees, any financial-performance information, franchisee openings and closures, and the agreement’s renewal, termination, and transfer terms. Have an independent franchise attorney review the documents and a CPA test the numbers against a slower-opening, lower-sales scenario.
Then speak with current and former franchisees listed in the FDD. Ask what opening really cost, how long it took to reach a sustainable level of sales, how many hours they work, what support they received, and whether they would make the same decision again. Compare their answers with the documents. A “franchise for sale” or an appealing projection is a starting point for questions, not proof of fit.
The SBA’s guidance on buying an existing business or franchise can help you explore financing considerations. A lender’s approval does not guarantee that a business is a sound investment. Ask about repayment terms, personal guarantees, required cash reserves, and how the loan would affect you if sales fall short.
Let the Runway Guide the Pace
A practical sequence is to stabilize your household finances first, define the work and lifestyle you want, compare a small number of franchise models, review the FDD with independent advisers, and speak with franchisees before committing. Set a decision date only after you understand the costs, contract, funding, and downside risks.
If the runway is short, that is useful information, not a reason to skip diligence. Slow down, keep other income options open, or wait until the decision can be made without putting essential funds at risk. A franchise can bring structure to a new chapter, but it cannot guarantee income or remove uncertainty.
How FranLift Can Help You Explore
FranLift helps prospective buyers clarify their goals and budget, research opportunities, and compare potential franchise matches. The service is free to prospective buyers because franchise companies cover its costs through their marketing budgets. Ask which brands are represented and how the process works, then conduct your own independent due diligence.
Learn why buyers work with FranLift or contact FranLift to discuss your goals.
FranLift is not a legal, tax, or financial advisor. Consult qualified independent professionals before making investment or financing decisions.
Launch Beyond Boundaries.
© 2026 FranLift. All rights reserved.
